Ask a room of day traders what their edge is and most will describe a setup, an indicator, or a feeling about the open. Ask them to prove it with their own numbers and the room goes quiet. That gap explains a lot. Research on day trader outcomes keeps finding the same pattern: a small minority stay profitable for long, and the rest never learn exactly why they lost. A trading edge is not a belief. It is a repeatable pattern that produces positive expectancy after costs, and you can only confirm it with records. This article explains why most day traders never find theirs, and how a day trading journal built around trade performance tracking turns scattered fills into evidence.
Table of Contents
- Quick Takeaways
- Why Most Day Traders Never Find an Edge
- The Numbers Behind the Failure Rate
- Edge Versus Activity
- What a Trading Journal Actually Captures
- Comparing Ways to Track Your Trades
- Building a Weekly Review Routine
- Common Journaling Mistakes
- Frequently Asked Questions
- References
Quick Takeaways
Key Insight | Explanation |
|---|---|
Define your edge in numbers before you defend it | Calculate expectancy as (average win x win rate) minus (average loss x loss rate), after commissions and slippage. If the result is negative, no setup name will save it. |
Count trades, not feelings | A pattern needs a large sample before you trust it. Ten trades can look like a strategy and average out to nothing over two hundred. |
Tag every trade with setup and context | Record setup type, catalyst, time of day, and market tone so you can filter performance by tag instead of by memory. |
Import fills automatically | Manual entry gets skipped after bad sessions, which are the days you most need the data. Broker import from DAS Trader Pro, Interactive Brokers, Schwab, or thinkorswim keeps the record complete. |
Journal before the open and after the close | A pre-market plan lets you compare what you intended with what you did. Post-market notes capture why the gap happened. |
Review by setup, not by total P&L | Total P&L hides the setup that carries the account and the one quietly draining it. |
Why Most Day Traders Never Find an Edge
Most day traders do not fail because they lack intelligence or effort. They fail because they never isolate what actually makes money in their own trading. A widely read market commentary on trader failure makes the same argument, placing the problem in the absence of effective, repeatable strategies rather than in a rigged market.
In practice, the typical pattern looks like this. A trader takes a dozen setups in a week, remembers the three that worked, and builds a story around them. The losers fade from memory because they hurt, and the wins stick because they feel like skill.
How memory edits your results
Without records, memory quietly rewrites the history in the trader's favor. A morning that ended with four small losses and one lucky runner often gets remembered as a good morning. The brain keeps the runner and forgets the rest.
This is why discretionary traders who swear they have an edge often cannot name it when asked. They have a general sense of their performance, but no measurement that would survive a second look.
Pro tip: Before you trust your memory of last week, export your fills and sort them by time. Most traders are surprised by how many of their "good days" were actually flat or negative after commissions.
Why a feeling is not a strategy
A setup you cannot define in writing is a mood, not a method. If you cannot state the entry trigger, the stop logic, and the conditions where the setup does not apply, you cannot test whether it works. The first job of a journal is to force that definition into words.
Once the setup is written down, you can ask a sharper question. Does this pattern produce positive results across different market conditions, or only on the days it felt right?
The Numbers Behind the Failure Rate
Survival rates by trading style
Figures vary by study, but they point in the same direction. One summary of day trading research reports that only about 13% of day traders are still in the business three years later, compared with 25% to 30% of short-term swing traders who survive that long. The gap suggests the difficulty is partly structural, tied to how often you act and how little room each trade has to work.
Another analysis puts the bar even lower. It reports that only 13% of day traders maintain consistent profitability over six months, and about 1% succeed over five years. Those numbers are harsh, but they also work as a filter. A trader who measures results is already doing something most of the field does not do.
Why one big winner rarely saves a day trader
Day trading has a batting average problem. A swing trader can hold a position for weeks and let one outsized winner cover a string of small losses. A day trader rarely gets that kind of runway, so friction, slippage, and small losing trades add up fast.
A review of 25 years of day trading research reports that in Brazil, 97% of persistent day traders (those active on 300 or more days) lost money in equity futures. Treat that as a warning about the activity itself, not a verdict on any one person. The practical lesson is that a trader needs a documented reason to believe they belong in the minority.
Edge Versus Activity
Why overtrading hides a missing edge
Activity feels like progress. Many day traders chase the stocks making the biggest moves of the day and try to catch a piece of that move. The problem is that intraday volatility is often random, and standard chart patterns work less reliably on very short time frames.
In practice, overtrading has a recognizable signature. Your trade count rises after a loss, your size drifts up after a win, and your best trades come in the first twenty minutes while your worst come after lunch. A journal shows those patterns within a month. Your memory will not show them at all.
Expectancy is the number that matters
A trading edge is measurable as expectancy, which is the average amount you make per trade after costs. A 40% win rate can be profitable if the winners are large enough, and a 60% win rate can lose money if the losers are oversized. Win rate alone tells you almost nothing.
Most day traders never calculate expectancy. They track win rate because it feels good, or total P&L because it is the number on the screen. Neither tells you whether the setup you are trading has positive expectancy on its own.
A win rate describes how a trader feels about their trades. Expectancy describes what the trades actually pay.
Pro tip: Calculate expectancy separately for each setup tag. If one setup is negative and you cannot explain why, pause it for two weeks and log what you would have done on each signal so the sample keeps growing without real risk.
What a Trading Journal Actually Captures
Broker import and trade fills
A useful day trading journal starts with raw data, which means trade fills. Manual entry sounds harmless until you skip it after a bad session, which is exactly when the data matters most. Automatic import closes that gap.
SpiceLog imports fills from DAS Trader Pro, Interactive Brokers, Schwab, thinkorswim, and PropReports, and it also accepts generic CSV files. Fills from several brokerages and journaling sources land in one view. That matters if you trade across more than one account or split time between a personal account and a prop firm evaluation.
Tags, setups, and the context around each trade
Raw P&L tells you very little. Tags turn each trade into a data point you can filter. Useful tags include setup type, catalyst, time of day, market tone, and whether the trade came from your written plan.
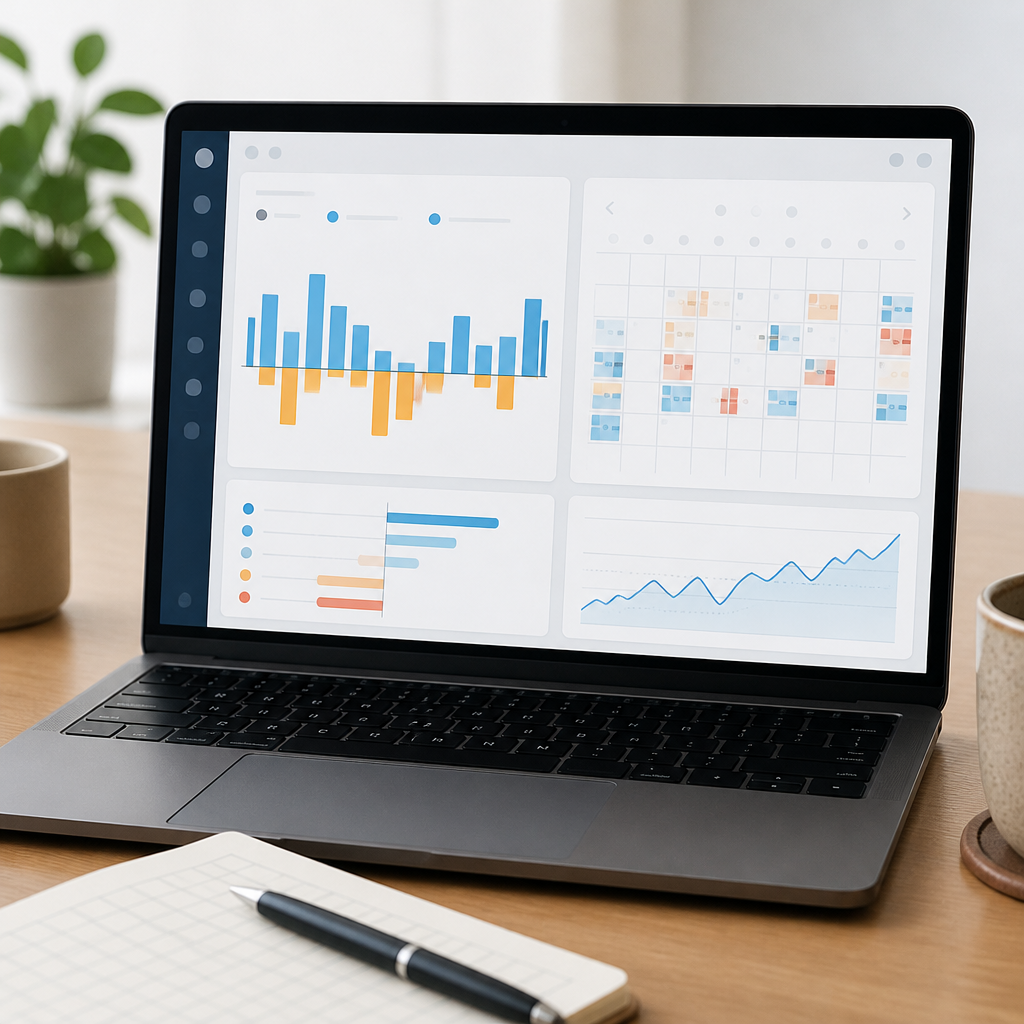
Trade tagging and performance analysis by tag lets you see, for example, that opening range breakouts carry the account while reversal attempts give it back. That is the difference between a feeling about your trading and an answer you can act on.
Pro tip: Keep your tag list to roughly eight to twelve items. A long list leads to inconsistent tagging within a few weeks, and inconsistent tags break the dataset you are trying to build.
Comparing Ways to Track Your Trades
Three approaches are common among active day traders. Each has a use, but only one gives you a reliable edge analysis at scale without relying on discipline to fill in blanks.
Approach | Strengths | Where It Breaks Down |
|---|---|---|
Broker statements only | Accurate fills and official records with no setup required | No tags, no setup context, and no expectancy by strategy. You get totals, not answers. |
Spreadsheet with manual entry | Fully customizable and free to start | Entries get skipped after bad sessions, and formulas become fragile as the log grows. |
Dedicated journal with broker import and tags | Complete fills, filterable tags, and performance by setup in one place | Requires an initial setup of tags and definitions, which must then be kept consistent. |
The spreadsheet is not wrong, it is just expensive in attention. Every manual entry is another chance to skip the trade you most need to review.
Features that matter more than the dashboard
Look for import from the brokers you actually use, tag-based filtering, pre-market and post-market notes, and a trading calendar that shows daily results next to your notes. Ignore charts that look impressive but cannot be filtered by setup. A pretty chart that cannot answer "which setup lost money last month" is decoration.
Building a Weekly Review Routine
Pre-market and post-market journaling
Write a short plan before the open: the two or three setups you will take, the price levels that invalidate them, and the maximum number of trades for the session. After the close, record what you actually did and compare it with the plan. The gap between those two is where most of your learning sits.
A trading calendar makes this routine stick. Each day shows P&L next to your notes, so bad days stay visible rather than being quietly forgotten by Friday.
The weekly review that finds the edge
Once a week, filter by setup tag and look at expectancy, average result per trade in R, and trade count. Then ask one question per setup: would I take this trade again knowing what I know now? Cut or pause anything that answers no across a meaningful sample.
Keep the review to 30 to 45 minutes. A longer session tends to turn into storytelling, and the point is to make a decision, not to write a diary entry about the week.
Pro tip: Use a position size calculator before each trade and log the planned risk in dollars. Comparing planned risk with actual risk shows whether your sizing rules hold up when the market moves fast.
Common Journaling Mistakes
Journaling only the winners
The most common mistake is logging the trades you are proud of. A journal that holds only winners is a highlight reel, and it will convince you of an edge you do not have. Log every fill, including the one you wish had not happened.
Reviewing too few trades
Thirty trades will not tell you much. Some setups look excellent over ten trades and average out to nothing over two hundred. Be willing to say the sample is too small, and keep collecting data before you change anything.
Another mistake is redefining tags every few weeks. If "breakout" means something different in March than it does in June, your analysis compares unlike things. Write each definition once, keep it visible, and change it only with a dated note explaining why.
Frequently Asked Questions
How do I know if I have a real trading edge or just good luck?
Measure expectancy per setup across a large sample, ideally several hundred trades, and check whether it stays positive across different market conditions. A short streak of wins does not prove anything. A positive expectancy that holds through choppy weeks and quiet weeks is much stronger evidence.
What should a day trading journal include at minimum?
At minimum, it should include every fill with time and price, a setup tag, the planned risk, a short pre-market plan, and a post-market note on what you actually did. Without the planned risk and the plan, you cannot tell whether you followed your rules or improvised.
How often should I review my trade performance?
Review quick notes at the end of each session, then do a deeper review once a week. Daily reviews tend to chase noise, while monthly reviews are too slow to catch a setup that has broken down. A weekly filter by setup tag hits the balance most traders need.
Is a spreadsheet good enough for tracking trades?
A spreadsheet can work if you enter every trade consistently and build the formulas carefully. Most traders struggle with the first part, especially after losing sessions. Broker import reduces that risk because the record fills in whether or not you feel like doing the paperwork.
Can a trading journal help prop firm traders as well as retail traders?
Yes. Prop firm traders often have strict daily loss and drawdown limits, so tracking planned risk and performance by setup matters even more. Importing fills from several accounts into one view also makes it easier to see how each evaluation or funded account is behaving.
If you have tracked your trades for a few months, I would like to hear what changed when you finally measured expectancy by setup. Share what you found, especially if it surprised you.
